ppagesxyzPlatform
JobsStudy GuidesFreeInterview Vault2.8k+Research & BlogCompaniesResume Review
Post a Job
ppagesxyzInstitutional Platform

The independent career intelligence, university-grade curriculum, and interview preparation resource for quantitative researchers, algorithmic traders, and high-performance software engineers.

Editorial BoardContact SupportExplore Free Curriculums →

Career Preparation

  • Interview Question Vault (2.8k+)
  • Probability Puzzles & Proofs
  • Market & Financial Engineering
  • Trading Brain Teasers
  • Quant Resume Review Service

Study Curriculums

  • Quantitative Finance Guide
  • Artificial Intelligence Track
  • Machine Learning Track
  • Data Science Curriculum
  • Low-Latency Software Engineering

Technical Research

  • Rust vs C++ in HFT Systems
  • Alternative Data & ML Alpha
  • RL Execution & Liquidity
  • Garden Leave & Non-Competes
  • Quant Salary & Bonus Guide
  • All Technical Articles & Guides

Firm Directory

  • Company Directory (450+)
  • Proprietary Trading Desks
  • Technology Organizations
  • Quant Startups & Market Makers
  • Post a Verified Opening

Trust & Legal

  • About & Technical Editorial Board
  • Editorial & Sourcing Policy
  • Privacy Policy (GDPR)
  • Terms of Use
  • Contact, Corrections & Privacy

Publisher & Editorial Standards

pagesxyz Media operates from Helsinki, Finland in compliance with European Union digital services standards. All curriculum tracks and worked solutions are authored and vetted by credentialed quantitative researchers and low-latency systems engineers.

Responsible Advertising & Disclosures

Advertising served through Google AdSense adheres strictly to Google Publisher Policies and EU GDPR consent frameworks. Display advertisements are clearly identified and do not influence curriculum recommendations or editorial rankings.

© 2026 pagesxyz Media. All rights reserved. Registered in Helsinki, Finland (EU).

Privacy Policy•Terms of Use•Editorial Guidelines•Contact
Home/Blog/Reinforcement Learning for Optimal Trade Execution and Liquidity Routing

Reinforcement Learning for Optimal Trade Execution and Liquidity Routing

ER
Dr. Elena Rostova• Principal Machine Learning & Alternative Data Researcher
•2026-10-24•Peer-Reviewed
Reinforcement Learning for Optimal Trade Execution and Liquidity Routing
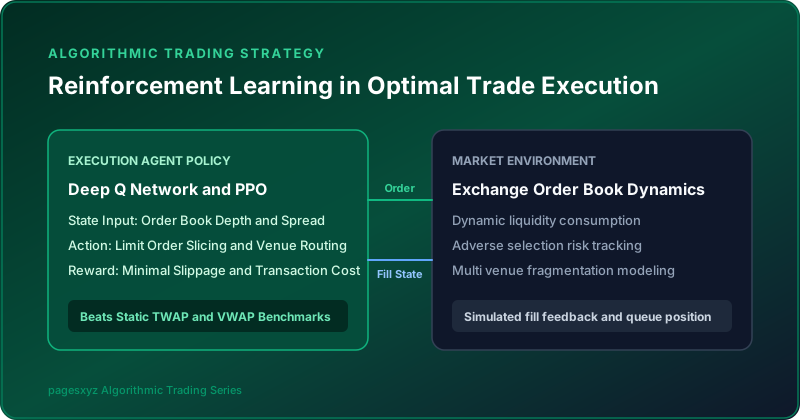
Closed loop reinforcement learning agent interacting with exchange order books

The Challenge of Large Institutional Order Execution

Executing large institutional orders without moving market prices is one of the most difficult challenges in quantitative finance. When an asset manager needs to purchase ten million shares of a liquid stock dumping the full size into the market triggers immediate price slippage. Other market participants detect the aggressive order flow and push prices higher before the order fills.

Why Rule Based TWAP and VWAP Strategies Fall Short

Standard algorithmic execution strategies like time weighted average price and volume weighted average price follow rigid schedules. A simple time based algorithm slices a large parent order into small child orders at fixed intervals. Predatory market participants exploit these predictable schedules by front running anticipated liquidity demands.

Formulating Trade Execution as a Reinforcement Learning Problem

Reinforcement learning offers a dynamic solution by treating execution as a sequential decision process. An artificial intelligence agent observes the current state of the limit order book and chooses optimal actions. The agent observes bid ask spread width queue depth order book imbalance and recent trade velocity across multiple market venues.

Passive Posting versus Aggressive Spread Crossing

The agent action space involves choosing when to post passive limit orders and when to cross the spread with aggressive market orders. Passive orders capture exchange maker rebates and avoid paying the half spread. However passive orders face execution risk if the market trends away before getting filled.

Reward Engineering and Adverse Selection Penalties

Designing an effective reward function is the core of reinforcement learning in trading. A simple reward based only on final fill price can encourage risky behaviors like delaying execution until the end of the trading day. Production systems incorporate penalty terms for inventory variance execution delay and adverse selection.

Multi Venue Liquidity Routing and Production Controls

Deploying reinforcement learning models into live production requires conservative safeguards. Trading desks run execution policies inside strict risk containers with hard limits on maximum participation rates and instantaneous slippage. Under proper risk controls reinforcement learning algorithms consistently beat standard static execution benchmarks.

Advertisementpagesxyz Sponsor Network
ER
Dr. Elena RostovaPhD in Machine Learning & Statistical Inference
Principal Machine Learning & Alternative Data Researcher

Focuses on deep reinforcement learning in execution algorithms, double machine learning for causal inference, LLM reasoning architectures, and NLP factor extraction for hedge funds.

View full bio & editorial board profile →

Explore Related Career & Technical Prep

📚
Study Guides

Full curriculums for quant finance, algorithms, stochastic calculus, and AI.

💡
Interview Vault

Real probability puzzles and financial math questions with worked solutions.

🏛️
Firm Directory

Hiring criteria, compensation benchmarks, and profiles of top market makers.