ppagesxyzPlatform
JobsStudy GuidesFreeInterview Vault2.8k+Research & BlogCompaniesResume Review
Post a Job
ppagesxyzInstitutional Platform

The independent career intelligence, university-grade curriculum, and interview preparation resource for quantitative researchers, algorithmic traders, and high-performance software engineers.

Editorial BoardContact SupportExplore Free Curriculums →

Career Preparation

  • Interview Question Vault (2.8k+)
  • Probability Puzzles & Proofs
  • Market & Financial Engineering
  • Trading Brain Teasers
  • Quant Resume Review Service

Study Curriculums

  • Quantitative Finance Guide
  • Artificial Intelligence Track
  • Machine Learning Track
  • Data Science Curriculum
  • Low-Latency Software Engineering

Technical Research

  • Rust vs C++ in HFT Systems
  • Alternative Data & ML Alpha
  • RL Execution & Liquidity
  • Garden Leave & Non-Competes
  • Quant Salary & Bonus Guide
  • All Technical Articles & Guides

Firm Directory

  • Company Directory (450+)
  • Proprietary Trading Desks
  • Technology Organizations
  • Quant Startups & Market Makers
  • Post a Verified Opening

Trust & Legal

  • About & Technical Editorial Board
  • Editorial & Sourcing Policy
  • Privacy Policy (GDPR)
  • Terms of Use
  • Contact, Corrections & Privacy

Publisher & Editorial Standards

pagesxyz Media operates from Helsinki, Finland in compliance with European Union digital services standards. All curriculum tracks and worked solutions are authored and vetted by credentialed quantitative researchers and low-latency systems engineers.

Responsible Advertising & Disclosures

Advertising served through Google AdSense adheres strictly to Google Publisher Policies and EU GDPR consent frameworks. Display advertisements are clearly identified and do not influence curriculum recommendations or editorial rankings.

© 2026 pagesxyz Media. All rights reserved. Registered in Helsinki, Finland (EU).

Privacy Policy•Terms of Use•Editorial Guidelines•Contact
Home/Blog/Machine Learning and Alternative Data in Quantitative Alpha Generation

Machine Learning and Alternative Data in Quantitative Alpha Generation

ER
Dr. Elena Rostova• Principal Machine Learning & Alternative Data Researcher
•2026-10-24•Peer-Reviewed
Machine Learning and Alternative Data in Quantitative Alpha Generation
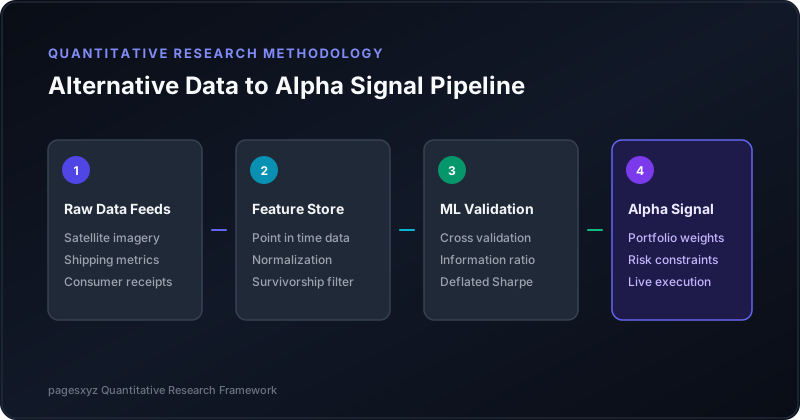
End to end pipeline from unstructured alternative feeds to live trading signals

The Decay of Traditional Market Price Signals

Quantitative hedge funds face continuous alpha decay as traditional price and volume signals become widely known. When hundreds of systematic strategies trade identical technical indicators market efficiency increases and profit margins compress. To maintain strong returns top research teams search for alternative datasets that capture economic reality before price adjustments occur.

Core Categories of Alternative Financial Datasets

Alternative data spans several distinct categories. Consumer transaction logs reveal daily retail spending patterns weeks before quarterly corporate earnings reports. Satellite imagery tracks shipping container movements around global ports and parking lot density outside major department stores. Financial natural language processing scans regulatory filings trade press and social sentiment to identify emerging operational risks.

Building Resilient Point in Time Feature Pipelines

Extracting raw data is only the initial hurdle. The most critical stage in alternative data research is point in time alignment. Many data vendors update historical databases retrospectively with revised figures. If a researcher trains an algorithm on restated historical data the model develops lookahead bias that fails completely in real trading.

Feature stores must preserve the exact timestamp when each piece of information became publicly available. Outliers survivorship bias and missing data intervals must be corrected before model training starts. Without rigorous normalization even the most sophisticated neural network will learn spurious noise.

Machine Learning Architectures for Signal Extraction

Modern research teams employ gradient boosted decision trees and deep learning architectures to process high dimensional feature vectors. Transformers and recurrent units excel at capturing sequential dependencies across unstructured textual disclosures. Graph neural networks model supply chain interdependencies between suppliers and manufacturers.

Strict Validation and Out of Sample Verification

Validation requires strict discipline. Researchers use purged cross validation to prevent information leakage between adjacent trading days. Metrics like deflated Sharpe ratio and out of sample information coefficient help distinguish genuine statistical edge from statistical overfit.

Live Portfolio Integration and Execution Considerations

A profitable signal must survive transaction costs and market impact. Signals derived from alternative data often trade at medium frequencies with holding horizons ranging from several days to several weeks. Firms that combine high quality feature pipelines with robust risk models capture sustainable profits in modern markets.

Advertisementpagesxyz Sponsor Network
ER
Dr. Elena RostovaPhD in Machine Learning & Statistical Inference
Principal Machine Learning & Alternative Data Researcher

Focuses on deep reinforcement learning in execution algorithms, double machine learning for causal inference, LLM reasoning architectures, and NLP factor extraction for hedge funds.

View full bio & editorial board profile →

Explore Related Career & Technical Prep

📚
Study Guides

Full curriculums for quant finance, algorithms, stochastic calculus, and AI.

💡
Interview Vault

Real probability puzzles and financial math questions with worked solutions.

🏛️
Firm Directory

Hiring criteria, compensation benchmarks, and profiles of top market makers.