ppagesxyzPlatform
JobsStudy GuidesFreeInterview Vault2.8k+Research & BlogCompaniesResume Review
Post a Job
ppagesxyzInstitutional Platform

The independent career intelligence, university-grade curriculum, and interview preparation resource for quantitative researchers, algorithmic traders, and high-performance software engineers.

Editorial BoardContact SupportExplore Free Curriculums →

Career Preparation

  • Interview Question Vault (2.8k+)
  • Probability Puzzles & Proofs
  • Market & Financial Engineering
  • Trading Brain Teasers
  • Quant Resume Review Service

Study Curriculums

  • Quantitative Finance Guide
  • Artificial Intelligence Track
  • Machine Learning Track
  • Data Science Curriculum
  • Low-Latency Software Engineering

Technical Research

  • Rust vs C++ in HFT Systems
  • Alternative Data & ML Alpha
  • RL Execution & Liquidity
  • Garden Leave & Non-Competes
  • Quant Salary & Bonus Guide
  • All Technical Articles & Guides

Firm Directory

  • Company Directory (450+)
  • Proprietary Trading Desks
  • Technology Organizations
  • Quant Startups & Market Makers
  • Post a Verified Opening

Trust & Legal

  • About & Technical Editorial Board
  • Editorial & Sourcing Policy
  • Privacy Policy (GDPR)
  • Terms of Use
  • Contact, Corrections & Privacy

Publisher & Editorial Standards

pagesxyz Media operates from Helsinki, Finland in compliance with European Union digital services standards. All curriculum tracks and worked solutions are authored and vetted by credentialed quantitative researchers and low-latency systems engineers.

Responsible Advertising & Disclosures

Advertising served through Google AdSense adheres strictly to Google Publisher Policies and EU GDPR consent frameworks. Display advertisements are clearly identified and do not influence curriculum recommendations or editorial rankings.

© 2026 pagesxyz Media. All rights reserved. Registered in Helsinki, Finland (EU).

Privacy Policy•Terms of Use•Editorial Guidelines•Contact
Home/Blog/Options Market Making and Volatility Surface Calibration in Practice

Options Market Making and Volatility Surface Calibration in Practice

AV
Dr. Alex Vance, PhD• Lead Quantitative Researcher & Technical Editor
•2026-10-24•Peer-Reviewed
Options Market Making and Volatility Surface Calibration in Practice
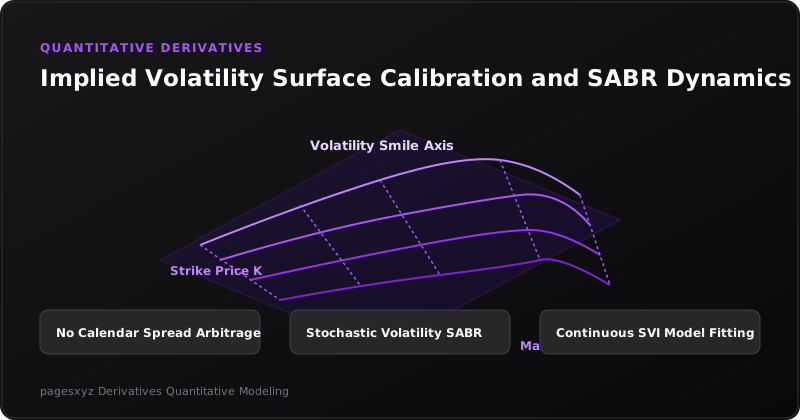
Three dimensional implied volatility surface across strike prices and maturities

The Complexity of Multi Strike Derivatives Books

Options market making is vastly more complex than trading underlying equities. A single equity or index can feature hundreds of listed put and call option contracts across multiple expiration dates and strike prices. A market maker must maintain two sided quotes on all active contracts while managing delta gamma vega and theta exposures.

Beyond the Black Scholes Flat Volatility Assumption

The classical Black Scholes pricing model assumes that asset returns follow a geometric Brownian motion with constant volatility. In real financial markets options implied volatility varies significantly across strike prices and maturities creating the well known volatility smile and skew.

Out of the money puts typically trade at higher implied volatilities due to market demand for downside catastrophe insurance. Market makers need dynamic continuous parametric models that capture this curvature across all strikes.

Parametric Surface Calibration with SABR and SVI

To calibrate continuous volatility surfaces quantitative desks employ specialized mathematical models like SABR stochastic volatility and Gatheral Stochastic Volatility Inspired SVI formulations.

SABR models the forward price and volatility as correlated stochastic processes providing closed form approximations for implied volatility. SVI models the total implied variance slice as a hyperbolic function of log moneyness ensuring smooth curves.

Strict No Arbitrage Enforcement

A critical requirement for automated options pricing is the absolute elimination of static arbitrage. An unconstrained mathematical curve fit can inadvertently generate calendar spread arbitrage or butterfly spread arbitrage where negative option probabilities emerge.

If a market maker publishes quotes containing butterfly arbitrage sophisticated algorithmic arbitrageurs will instantly execute risk free trades against the firm. Calibration algorithms enforce non negative risk neutral density across all evaluated strikes.

Real Time Hedging and Portfolio Risk

Once quotes fill market makers immediately hedge their underlying delta exposure by trading futures or underlying cash stocks. Residual gamma and vega risks are managed across the aggregate book through cross asset balancing and structured risk envelopes.

Advertisementpagesxyz Sponsor Network
AV
Dr. Alex Vance, PhDPhD in Applied Mathematics (Stochastic Calculus & PDE Analysis)
Lead Quantitative Researcher & Technical Editor

Former quantitative researcher at proprietary market-making firms. Specializes in stochastic volatility calibration, order flow microstructure, and mathematical foundations of trading interviews.

View full bio & editorial board profile →

Explore Related Career & Technical Prep

📚
Study Guides

Full curriculums for quant finance, algorithms, stochastic calculus, and AI.

💡
Interview Vault

Real probability puzzles and financial math questions with worked solutions.

🏛️
Firm Directory

Hiring criteria, compensation benchmarks, and profiles of top market makers.